Market Overview: Defining the Transmission Fluids Market
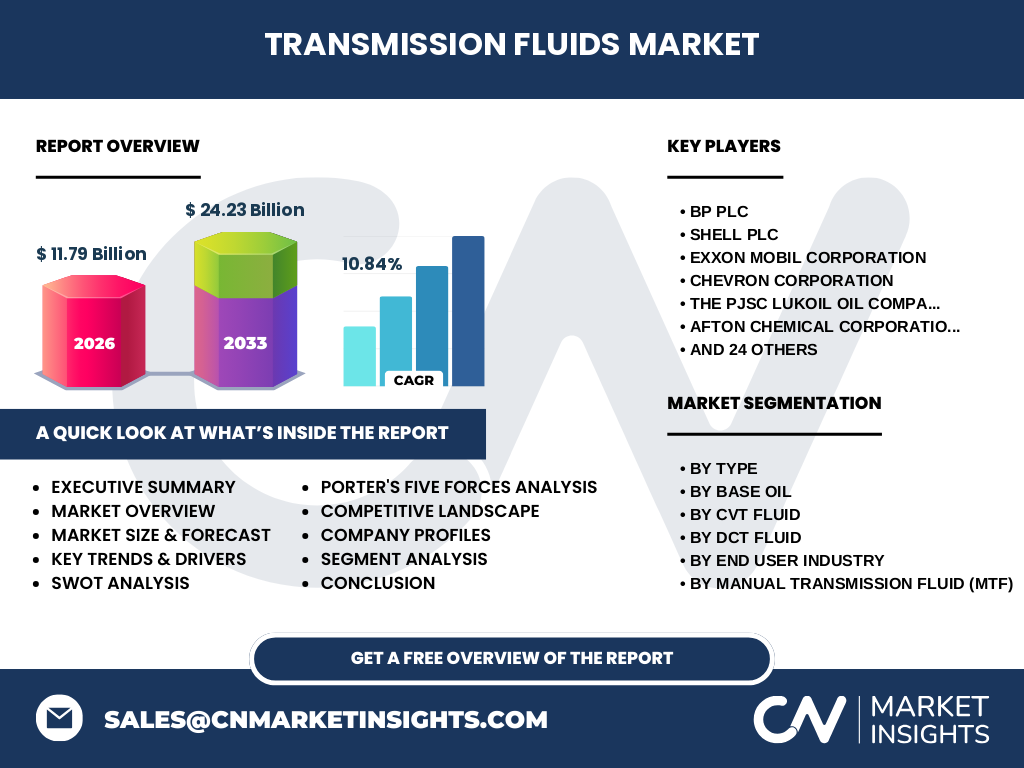
The Transmission Fluids Market encompasses essential lubricants engineered to minimize friction and thermal degradation in vehicular power transmission systems. As of 2026, the market is valued at 11.79 Billion, playing a critical role in the operational longevity of automotive, mining, and industrial machinery. These fluids act as specialized hydraulic media, critical for power transfer and heat dissipation in complex mechanical gearsets.
Structural Growth Drivers and Market Restraints
The market is propelled by a CAGR of 10.84%, primarily driven by expanding urbanization and industrialization in emerging economies. Conversely, technological transitions toward electric vehicle powertrains act as a potential restraint. While internal combustion engine (ICE) support remains robust, manufacturers must balance logistical hurdles in sourcing high-performance synthetic additives amidst tightening environmental regulatory frameworks.
Emerging Trends and Strategic Growth Patterns
A pivot toward low-viscosity, fuel-efficient fluids defines the current landscape. We observe a significant shift in the Transmission Fluids Market as OEMs demand specialized solutions for dual-clutch and continuously variable transmissions. This trend favors agile innovators like ZF Friedrichshafen AG and The Lubrizol Corporation, who are prioritizing R&D into heat-stable, long-drain interval formulations to improve fleet efficiency.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic caused initial supply chain volatility and reduced automotive throughput; however, the market exhibited resilience through the recovery trajectory. Post-2022, increased demand for heavy-duty construction and mining machinery offset passenger vehicle stagnancy. Data suggests that normalized supply chains have stabilized raw material procurement, positioning the market for aggressive expansion toward the 24.23 Billion milestone by 2033.
Competitive Benchmarking and Strategic Dynamics
The landscape features a high degree of market concentration, dominated by incumbents like Shell PLC, Exxon Mobil Corporation, and BP PLC. These majors leverage vertically integrated value chains to maintain market share. Smaller, specialized firms such as AMSOIL Inc. carve niches in high-performance segments, creating a dynamic environment where strategic partnerships with OEMs are the primary barrier to entry.
Executive Summary: Synthesis of Market Findings
The Transmission Fluids Market is poised for substantial growth, moving from 11.79 Billion in 2026 to a projected 24.23 Billion by 2033. Our analysis highlights that while traditional ATF segments remain foundational, the shift toward synthetic formulations for CVT and DCT applications is where future alpha lies. This report provides the necessary granular intelligence to navigate this evolving lubricant ecosystem.
Projected Market Forecast 2027 to 2033
Projections indicate the market will hit 24.23 Billion by 2033, expanding at a steady CAGR of 10.84%. This trajectory assumes consistent adoption of advanced synthetic fluids and increased industrial utilization in mining and infrastructure sectors. We anticipate that geographic expansion in the APAC region will serve as a core accelerator for these long-term revenue targets.
Segmentation Analysis: Deep Dive into Product Categories
Segmentation is categorized by Type (ATF, MTF, CVT, DCT) and Base Oil (Mineral, Synthetic, Semi-Synthetic). The Synthetic segment is seeing the fastest adoption due to superior performance in extreme thermal conditions. Each segment addresses specific mechanical stressors, with CVT and DCT fluids representing the highest growth potential as modern transmission designs require more sophisticated, chemically engineered lubricant profiles.
Regional Market Analysis: Geographic Performance
The market displays distinct geographic distribution. North America and Europe dominate through mature automotive consumption, whereas the APAC region is the fastest-growing hub. Localized constraints, such as differing emission standards between the EU and China, require suppliers to adapt their product portfolios. Major ports in Singapore and Rotterdam remain critical hubs for the logistical distribution of these specialized chemical products.
In-depth Regional Review: Key Regional Markets
Asia-Pacific remains the engine of growth, supported by heavy industrialization in India and China. Regional giants like Indian Oil Corporation Ltd. and China National Petroleum Corporation are scaling local capacity to meet domestic industrial machinery demands. Meanwhile, North American markets focus on high-performance synthetic fluids for light-duty trucks, reflecting localized consumer preferences for towing capacity and vehicle longevity.
Company Profiles: Strategic Positioning of Industry Leaders
Leading players like Chevron Corporation and TotalEnergies SE utilize deep R&D to maintain technical superiority. FUCHS PETROLUB SE is notably positioned as a premium supplier to automotive OEMs, while Petronas Lubricants International focuses on global expansion through aggressive strategic partnerships. These firms effectively manage market volatility by diversifying their product offerings across both the automotive and heavy-duty industrial sectors.
Porter’s Five Forces Analysis
The Transmission Fluids Market exhibits moderate supplier power due to concentrated base oil production. However, buyer power is high among large-scale automotive OEMs. The threat of new entrants is low due to stringent regulatory certification processes. Conversely, the intensity of rivalry is high, forcing incumbents to constantly innovate their synthetic chemical compositions to remain competitive against emerging high-performance lubricants.
SWOT Analysis: Strategic Evaluation
Strengths include robust demand in emerging economies; Weaknesses involve high sensitivity to base oil price fluctuations. Opportunities abound in the development of specialized e-fluids for electrified powertrains, while Threats remain centered on the global transition toward EVs, which may eventually reduce demand for traditional transmission-specific lubricants in some segments.
Value Chain Analysis: From Raw Materials to End-Users
The value chain originates with the refining of crude oil and synthetic base stocks, followed by additive package blending. Key players like The Lubrizol Corporation focus on the chemical formulation phase, essential for meeting OEM specifications. Finished fluids are then channeled through automotive distributors and industrial suppliers to end-users in the mining, construction, and automotive sectors, ensuring efficient power management.
Investment Insights and High-Potential Areas
Investors should prioritize companies focusing on high-performance synthetic MTF and DCT fluids. The data suggests that market participants capable of developing heat-resistant, low-viscosity solutions are gaining significant competitive advantage. Strategic investments in the APAC industrial sector offer high potential as infrastructure spending increases, necessitating reliable, long-life transmission maintenance fluids for heavy machinery and fleets.
Conclusion and Key Takeaways
The Transmission Fluids Market is resilient and evolving. With a valuation reaching 24.23 Billion by 2033, the industry demonstrates robust health. Success hinges on mastering synthetic formulation technology and navigating the regional regulatory landscape. The transition toward advanced transmission types (CVT, DCT) provides a clear path for growth that outweighs the risks posed by powertrain electrification trends.
Research Methodology: How Baseline Estimates are Triangulated
Our analysis employs a triangulation approach, combining trade registry data, annual report filings from industry leaders like Valvoline Inc., and secondary macroeconomic indicators. We conducted primary stakeholder interviews with procurement managers in the mining and automotive sectors to validate growth trends, ensuring our baseline projections for the 10.84% CAGR remain both grounded and actionable for stakeholders.
Scope of the Report: Parameters and Limitations
This report covers the global Transmission Fluids Market across 2026–2033, including all major product types and end-user segments. While the scope is comprehensive, it is limited by the unpredictability of global geopolitical tensions affecting shipping routes and the pace of EV adoption. The data specifically focuses on formal lubricant markets and does not account for grey-market volumes or unverified local supply chains.
Recent Developments: Industry Announcements and Partnerships
Recent activity highlights a focus on sustainability and innovation. Companies like Neste Oyj are increasingly integrating renewable base oils into their portfolios, while major partnerships between SK Lubricants Co. Ltd. and automotive OEMs demonstrate a commitment to custom-engineered fluid solutions. These strategic moves are essential for meeting the stringent technical requirements of modern high-performance vehicles, ensuring growth through the 2033 forecast period.